Refinancing an Investment Property Portfolio: Why Your Broker Relationship Matters
Short answer: Refinancing an investment property portfolio works best as a planned review of rates, loan structure, interest-only expiry dates, equity, serviceability and lender spread, not a reaction to one lower advertised rate. Check the costs and your next purchase plan first, then use a broker who understands investors.
Refinancing an investment property portfolio is not just about chasing a cheaper interest rate. For investors with multiple loans, a refinance can affect cash flow, equity access, borrowing capacity, lender exposure, interest-only periods and the timing of the next purchase.
SLScott LevouneFounder, Wealth Through PropertyUpdated 30 Oct 2026•8 min read•✓ Facts checked against official sources
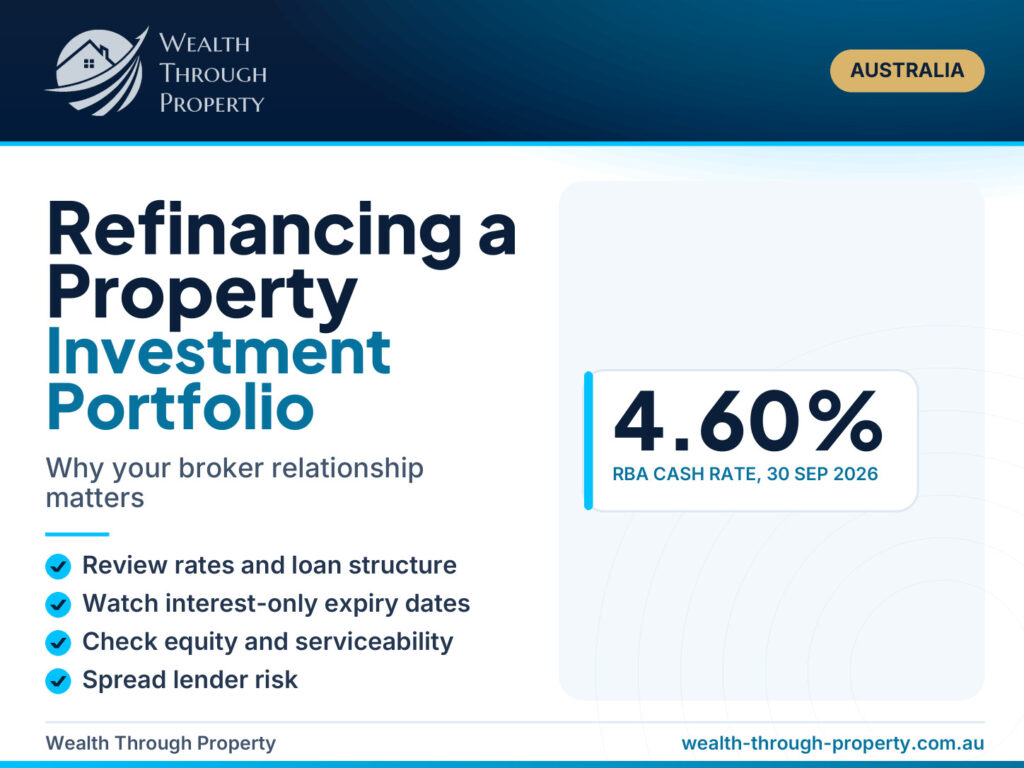
Portfolio refinancing should be planned, not reactive. Investors need to review rates, loan structure, interest-only expiry dates, equity position, serviceability, lender spread and future purchase goals before changing lenders or releasing equity. Test every option against the whole portfolio, including costs, buffers and the next property you want to buy.
Before You Refinance
A lower rate can be useful, but the broader lending position matters. Refinancing too quickly, too often or without a plan can create costs, friction or reduced flexibility. Before you move, check loan age, fixed-rate status, break costs, discharge fees, valuations and interest-only expiry dates, then compare the saving with the cost of switching.
1Review timing: Check loan age, fixed-rate status, interest-only expiry dates, valuations and possible switching costs before moving.
2Check portfolio impact: Consider cash flow, borrowing capacity, equity access, lender concentration and the next purchase plan together.
Refinancing Is a Portfolio Decision, Not Just a Rate Decision
Many investors start thinking about refinancing when they see a lower advertised interest rate. That is understandable, but it is also too narrow. A property portfolio is not one isolated loan. It is a collection of assets, debts, rental income, repayment obligations, lender policies, cash buffers and future plans.
A refinance can improve the position. It may reduce interest costs, reset an interest-only period, release usable equity, separate loans more cleanly or move a property to a lender that better suits the next stage of the plan. It can also create problems if it is done without enough thought.
A cheaper rate helps when the refinance also supports the portfolio’s risk position, cash flow and next-step strategy.
Moving too early may trigger unnecessary costs or create relationship issues with the broker. Moving to the wrong lender can reduce future flexibility. Releasing equity without a clear purpose can increase debt without improving the investment strategy.
This is why a strong broker relationship matters. A broker who understands investors should look beyond the loan being refinanced. They should understand what the investor is trying to build, how the current loans interact, which lenders have already been used, when interest-only periods expire, what cash-flow pressure exists and whether another purchase is being considered.
For investors still buying, lending strategy and acquisition strategy need to speak to each other. A property may look strong on the research side, but if the lending position is poorly structured, the next purchase can become harder than expected. Working with an investment property buyers agent can help keep the buying brief, due diligence and finance conversations aligned before committing to a deal. For the wider picture, read our guides to cash flow in property investment and buying property in Australia in 2026.
When Refinancing Can Be Worth Reviewing
There is no single refinance date that suits every investor. The right timing depends on loan terms, lender policy, market conditions, costs, portfolio goals and the investor’s broader financial position. That said, there are common review points that should not be ignored.
Rate movement
If the current loan is no longer competitive, a broker may be able to negotiate with the existing lender or compare refinance options.
Interest-only expiry
Investors using interest-only repayments need to know when the period ends and what the repayment change may look like.
Equity movement
If property values have increased, refinancing may create options to access equity, subject to lender policy, serviceability and risk tolerance.
Future purchase plans
The next loan can be affected by the current lender mix, repayment type, buffers, debt position and serviceability assessment.
Interest-only periods deserve particular attention. Many investors use interest-only repayments to preserve cash flow while building a portfolio. That can make sense in some circumstances, but the expiry date needs to be managed. When a loan rolls from interest-only to principal-and-interest, repayments can rise. If that shift happens across several loans close together, the portfolio can feel very different.
A proactive broker should not wait until the investor notices the repayment change. They should help monitor key dates, explain what options may be available and assess whether a reset, renegotiation or refinance is appropriate.
The answer will not be to refinance every time. Sometimes the current lender can improve the rate. Sometimes the costs do not justify the move. Sometimes the investor’s serviceability has changed and the better strategy is to wait, prepare or restructure more carefully.
Rate is one part of the decision
A lower rate is attractive, but repayment type, lender policy, offset structure, valuation outcome, equity access, fees and future borrowing position can matter just as much.
Investors should also connect refinancing decisions to cash flow in an Australian property portfolio. A portfolio that looks fine on paper can become uncomfortable if rent, repayments, vacancy, insurance, maintenance, land tax and other holding costs are not reviewed together.
What a Good Broker Should Understand About Property Investors
A broker working with investors needs a different level of context from a broker handling a simple owner-occupier loan. The loan might look straightforward, but the portfolio rarely is. They should know every loan, lender, repayment type, buffer and goal across the portfolio, not just the loan being refinanced.
A good broker should understand how each property is held, whether loans are cross-collateralised, which lenders are already in use, how much equity may be available, what buffers exist and what the investor plans to do next.
They also need to understand the investor’s behaviour. Some investors want to buy again soon. Others need to consolidate and improve cash flow. Some are approaching a serviceability limit. Others may need to review ownership structures, trusts or companies with qualified professionals.
A broker cannot replace financial, tax or legal advice, but they should know when those conversations need to happen before a lending change is made. This is where structure becomes important. The article on property investment structures and SPVs is a useful supporting read because lending, ownership, land tax, borrowing capacity and asset protection can all interact.
1Lender spread: Using the same lender repeatedly may feel simple, but it can affect flexibility as the portfolio grows.
2Loan purpose: Equity release should have a clear purpose, whether for future investment, buffers, improvements or debt management.
3Cash-flow pressure: Repayment changes should be modelled before they arrive, especially when multiple interest-only periods are ending.
A good broker should also be willing to say no or not yet. That can frustrate investors who want immediate action, but it can be the responsible answer. If the refinance cost outweighs the benefit, if serviceability is weaker than expected, if lender options are limited or if a quick refinance damages a better future option, pausing can be sensible.
The best broker relationship is not built on saying yes to every refinance. It is built on knowing which move protects the portfolio and which move creates unnecessary risk.
For investors who want to stay hands-on but build more confidence around research, strategy and decision-making, property mentoring can help with understanding the steps that sit around the purchase, portfolio review and due diligence process.
The Broker Relationship Has to Work Both Ways
A broker is a service provider and also runs a business. Lenders usually pay brokers, and refinancing soon after settlement can trigger a clawback of commission, which is why timing matters. Be open about timing, costs and goals so both sides can plan the move properly.
This does not mean investors should avoid refinancing when it is clearly in their interest. It means the conversation should be transparent. A good broker can explain the benefits, costs, lender options, possible clawback considerations and whether waiting a little longer may produce a cleaner result.
A good investor should respect that advice while still expecting the broker to advocate strongly where action is justified. The relationship works best when both sides are clear about timing, costs, goals and risk.
Regular reviews are usually more useful than reactive refinancing.
An annual portfolio review can check rates, repayment types, interest-only expiry dates, equity movement, offset use, lender exposure and serviceability. It can also help the investor plan the next purchase before the buying opportunity appears.
Waiting until a contract is signed or an auction is approaching can reduce options. The finance side of the plan should be reviewed before the next property decision becomes urgent.
Investors should also keep their own numbers updated. Rental income, expenses, loan balances, repayment changes and buffers should be reviewed regularly. Wealth Through Property’s resources and calculators can help with basic modelling, but individual lending, tax, legal and financial advice may still be needed before making decisions.
Refinancing Should Not Hide Weak Asset Selection
Refinancing can improve a portfolio’s position, but it should not be used to avoid the fundamentals. If a portfolio is under pressure because the assets have weak rent, poor tenant demand, high costs, limited growth fundamentals or ongoing maintenance issues, a refinance may buy time but it does not fix the underlying problem.
Strong lending strategy works best when it is paired with strong buying strategy, clear due diligence and disciplined portfolio management. Before adding another property or releasing equity for the next step, investors should review the assets they already hold and the assumptions sitting behind the plan.
This includes rental evidence, comparable sales, days on market, vacancy risk, holding costs, insurance, strata, maintenance, land tax exposure and the quality of the local demand drivers. For more on assessing the property before you buy, read the guide to data-driven due diligence for property investors.
Need a clearer investment buying and portfolio review process?Get support with strategy, suburb research, property assessment, due diligence, negotiation and the broader thinking that should happen before your next purchase or refinance.
Refinancing decisions now sit against a higher cash rate, tighter lending limits and a quieter June quarter for investor lending, so it pays to check the official figures before you move. These three facts were checked against primary sources on 28 October 2026 and are a sound starting point for any portfolio review.
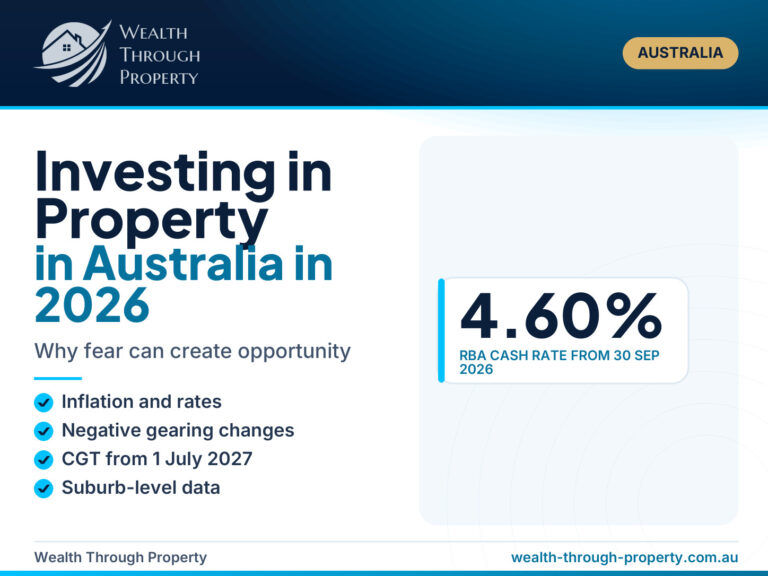
As checked on 28 October 2026, the Reserve Bank of Australia cash rate target is 4.60 per cent, after a 0.25 percentage point rise decided on 29 September 2026 and effective from 30 September 2026.
As checked on 28 October 2026, APRA allows lenders to write up to 20 per cent of new investor lending at a debt-to-income ratio of six times income or more from 1 February 2026, and its mortgage serviceability buffer stays at 3 percentage points.
As checked on 28 October 2026, the ABS reports that new investor loan commitments for dwellings fell 8.6 per cent in number and 10.2 per cent in value in the June quarter 2026, and these dwelling commitment figures exclude refinancing.
This article is general information and not personal financial, credit, tax or legal advice. Speak with a licensed broker and your accountant before you change any loan.
FAQs About Portfolio Refinancing for Investors
When should property investors review their loans?
Many investors benefit from at least an annual loan review, especially if they hold multiple properties. It can also be worth reviewing sooner when interest-only periods are expiring, rates have moved, equity has changed or another purchase is being planned.
Is refinancing worth it just because the rate is lower?
No. A lower rate can help, but investors also need to consider fees, lender policy, repayment type, valuation outcomes, serviceability, equity access and future borrowing flexibility. The numbers need to support the decision.
Why does an interest-only expiry matter?
When an interest-only period ends, repayments may change to principal-and-interest. That can increase holding costs and affect cash flow, especially if several loans change around the same time.
Can refinancing help investors access equity?
It may, depending on property values, lender policy, income, debt position, loan-to-value ratio and serviceability. Accessing equity should have a clear purpose and should be assessed with appropriate lending and financial advice.
Why is a strong broker relationship important for investors?
A strong broker relationship helps keep the lending side of the portfolio organised. A proactive broker can monitor rates, expiry dates, lender exposure and refinancing options before the investor is forced into a rushed decision.
Should refinancing be planned before buying the next property?
Yes, where possible. The current lending structure can affect the next purchase. Reviewing loans, equity, serviceability, buffers and lender options before buying can help avoid surprises during due diligence or negotiation.
How much does it cost to refinance an investment property?
Costs vary by lender and loan. Check discharge fees on the old loan, any fixed-rate break costs, application or valuation fees on the new loan and possible lenders mortgage insurance. Compare the total with the saving before you switch.
How does the Reserve Bank cash rate affect refinancing decisions?
The cash rate target is 4.60 per cent as checked on 28 October 2026. A rate rise often prompts investors to review loans, but a lender's rate can differ from the cash rate, so compare real offers and costs rather than assuming a move will save money.
Show 2 more questionsShow fewer questionsDoes a broker have to give back commission if I refinance soon after settlement?
Lender agreements can allow commission to be clawed back if a loan is repaid early, which is why timing matters. Ask your broker how the lender terms work and whether waiting would change the result before you decide.
Is it better to refinance all investment loans at once?
Not necessarily. Moving every loan together can concentrate risk with one lender and affect cross-collateralised security. Review each loan on its own numbers, then decide which to move, which to renegotiate and which to leave where they are.
SL
About the author
Scott Levoune
Founder of Wealth Through Property. Scott built a portfolio of 10 investment properties in 3 years, then built the pricing system that turned his own Airbnb into one of the top earners on the NSW South Coast. He and the team now buy, set up and manage short-stay homes across Australia.
When should property investors review their loans?
Many investors benefit from at least an annual loan review, especially if they hold multiple properties. It can also be worth reviewing sooner when interest-only periods are expiring, rates have moved, equity has changed or another purchase is being planned.
Is refinancing worth it just because the rate is lower?
No. A lower rate can help, but investors also need to consider fees, lender policy, repayment type, valuation outcomes, serviceability, equity access and future borrowing flexibility. The numbers need to support the decision.
Why does an interest-only expiry matter?
When an interest-only period ends, repayments may change to principal-and-interest. That can increase holding costs and affect cash flow, especially if several loans change around the same time.
Can refinancing help investors access equity?
It may, depending on property values, lender policy, income, debt position, loan-to-value ratio and serviceability. Accessing equity should have a clear purpose and should be assessed with appropriate lending and financial advice.
Why is a strong broker relationship important for investors?
A strong broker relationship helps keep the lending side of the portfolio organised. A proactive broker can monitor rates, expiry dates, lender exposure and refinancing options before the investor is forced into a rushed decision.